

Fannie Mae and Freddie Mac are moving toward allowing lenders to use VantageScore as an additional credit scoring option for mortgage underwriting. This shift could expand access to mortgage credit, streamline application processing, and provide a more flexible view of borrower creditworthiness. Here’s what homebuyers and industry professionals need to know.
What’s changing
Historically, Fannie Mae and Freddie Mac have relied primarily on FICO scores for automated underwriting and eligibility.
The proposed change will permit lenders to use VantageScore models (likely VantageScore 4.0 or newer) alongside FICO when evaluating mortgage applicants for loans that will be delivered to the GSEs.
Implementation will follow finalization of policy guidance, testing, and a transition timeline from the GSEs.
Why this matters
Greater inclusion: VantageScore uses a different scoring model and can score more consumers (for example, those with thin or nontraditional credit files). Borrowers with limited credit histories may now qualify more easily.
Potentially different results: VantageScore and FICO use different algorithms, weightings, and treatment of certain data (like most recent activity or public records). A borrower’s VantageScore may be higher or lower than their FICO score.
Lender flexibility: Lenders will have an additional tool for assessing risk, potentially improving underwriting efficiency and enabling automated approvals in more cases.
Competition and pricing: Over time, broader use of VantageScore could influence market competition among credit scoring providers and might affect how lenders price loans.
What homebuyers should do
Check both scores: Request or review both your FICO and VantageScore where available so you understand how each model views your credit.
Improve key factors: Both models reward on-time payments, low credit utilization, a mix of credit types, and reasonable account age. Focus on paying bills on time, reducing balances, and avoiding new hard inquiries before applying.
Provide clear documentation: If you have thin credit or nontraditional credit history, work with your lender to document stable income, rent payment history, and other evidence of reliability.
Shop lenders: Different lenders may adopt VantageScore at different rates. If your VantageScore is stronger than your FICO, seek lenders who will accept or consider VantageScore for underwriting.
What lenders and brokers should prepare
System updates: Update automated underwriting systems, decisioning rules, and disclosures to incorporate VantageScore.
Validation and training: Run parallel testing to compare outcomes between FICO-based and VantageScore-based underwriting. Train loan officers and processors on differences and implications for pricing and eligibility.
Policy and compliance: Ensure compliance teams validate model performance across borrower segments and document rationale for use, especially for loans that will be sold to the GSEs.
Communication: Clearly explain to borrowers which score(s) are being used and how differences may affect eligibility and rate offers.
Limitations and considerations
Not a guaranteed approval: Use of VantageScore does not change fundamental underwriting standards—credit score is one of many factors (income, assets, debt-to-income, property appraisal).
Score variability: Expect that scores will not be equivalent; lenders may require specific score types for certain products or overlays.
Rollout timing: Adoption will be phased; lenders and secondary market participants will take time to implement and validate changes.
Bottom line Allowing VantageScore as an alternative scoring model for loans delivered to Fannie Mae and Freddie Mac could increase access to mortgage credit for some borrowers and give lenders more flexibility. Buyers should monitor both credit scores, improve the fundamentals of credit health, and work with lenders who transparently incorporate VantageScore when it benefits the borrower’s application. If you’re preparing to buy, review your credit profile now so you’re ready when you apply.
Welcome, September!
Today, I’m starting the month with a hike, some fresh air, and an important message for homebuyers and sellers.
Right now, mortgage rates are not moving in a direction that improves affordability. The average 30-year fixed mortgage is around 6.76% today, compared with Freddie Mac’s weekly benchmark of 6.66% last Thursday.
The bottom line is that mortgage rates remain in the upper-6% range.
Buyers, if you’re waiting for rates to reach exactly 5.99% before you even begin looking, you’re allowing something you cannot control to determine when you start preparing.
Preparing doesn’t mean you have to buy today. It means understanding your credit, establishing a comfortable monthly budget, speaking with a lender, and learning what options may be available to you.
And sellers, affordability is putting pressure on buyers. That means your pricing, presentation, and willingness to consider incentives—such as closing-cost assistance or a temporary rate buydown—can make a meaningful difference.
You cannot control mortgage rates, but you can control how well-prepared you are. Let’s welcome September with a clear plan and an open mind.
My priority is to give you the highest quality of service whether you are buying or selling.
I provide personalized guidance at every stage—accurate market analysis, tailored home searches, strategic pricing, skilled negotiation, and seamless transaction management. You’ll receive timely communication, honest advice, and practical solutions designed to meet your goals and protect your interests.
If you’re buying: I’ll help you identify properties that match your priorities, set realistic offers, coordinate inspections and financing, and move efficiently from offer to closing.
If you’re selling: I’ll prepare your home to attract the right buyers, recommend competitive pricing, craft compelling marketing, manage showings, and negotiate the best terms on your behalf.
Your needs come first. Contact me today so we can outline your goals and create a plan that delivers results.
Why work with me
What I will provide for you
Clear communication from start to finish — timely responses, straightforward explanations, and proactive updates.
Reliable, high-quality work delivered on schedule and to agreed specifications.
Personalized attention — I tailor solutions to your needs and preferences, not a one-size-fits-all approach.
Professionalism and respect — your time, property, and priorities are treated with care.
Problem-solving and accountability — if anything goes wrong, I take responsibility and make it right.
Transparent pricing and no hidden fees — you’ll always know what to expect.
Follow-up support — I ensure you’re satisfied after the job is complete and available for any questions.
My goal is to earn your trust through exceptional service so you’ll happily recommend me to those you care about., so that at the end of my service you can clearly recommend me to family, neighbors, and friend,
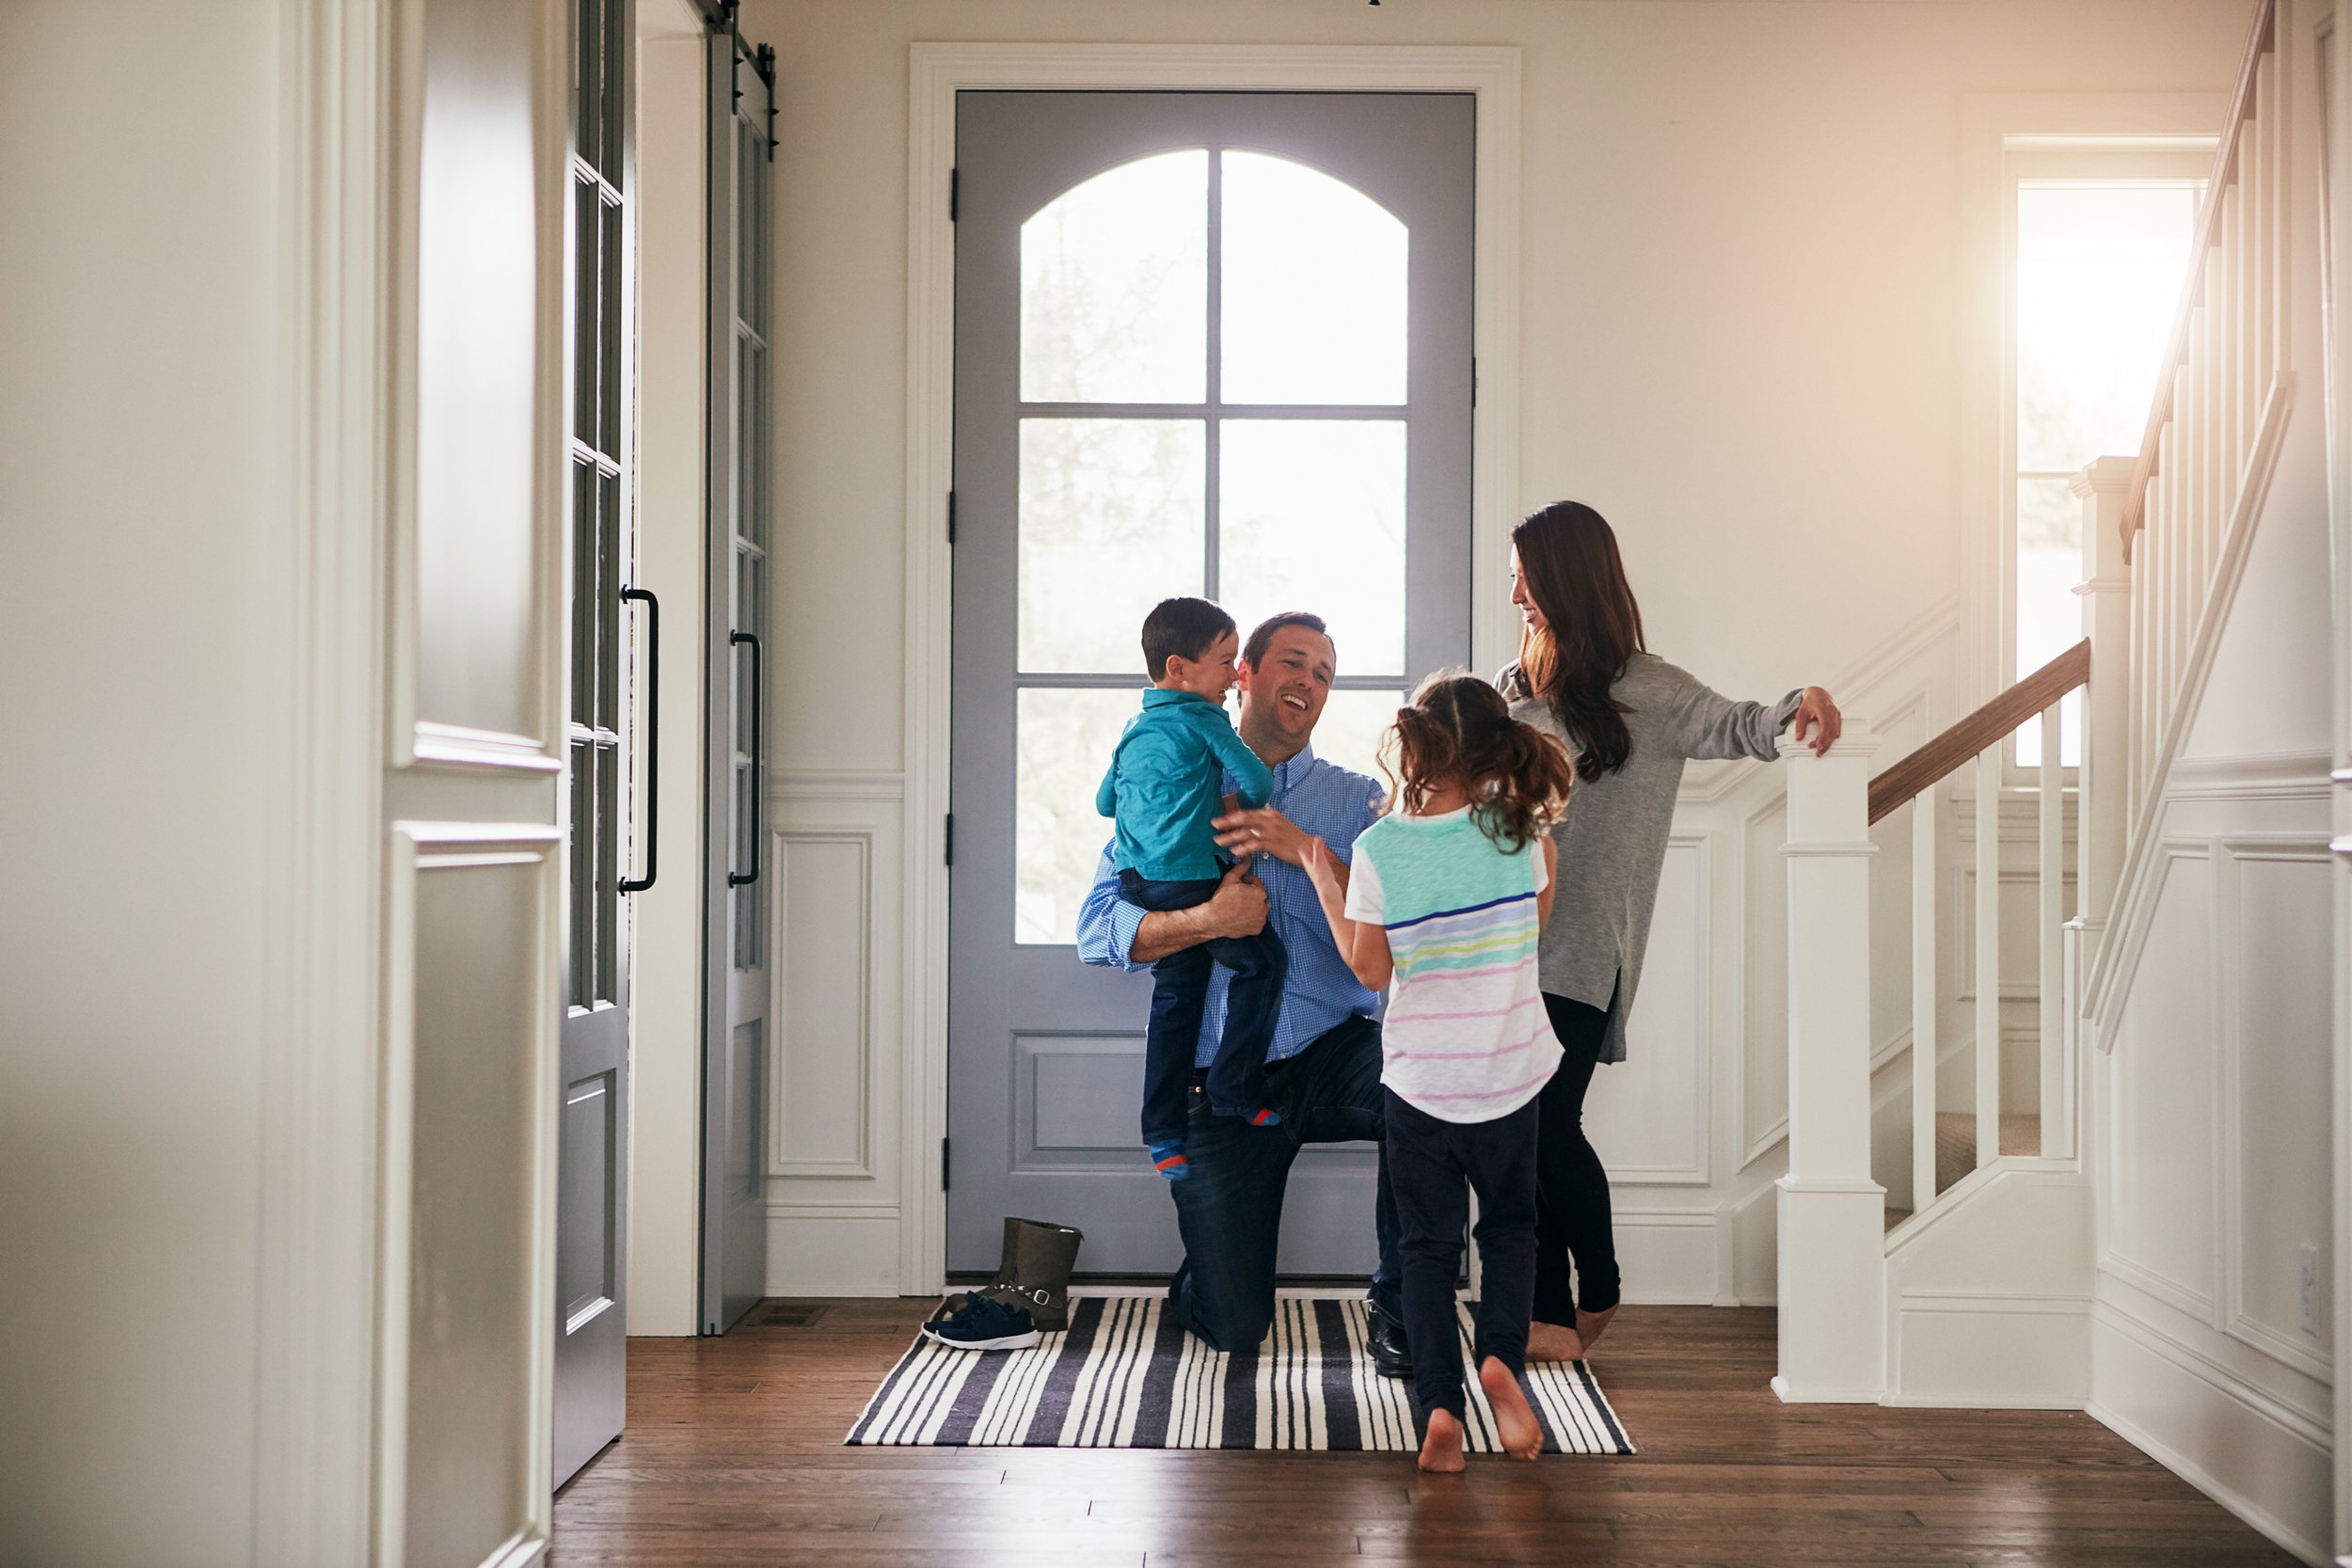
Love to see families enter their new home
It’s always a joy to see families enter their new home, even when it’s just for an open house. They arrive with laughter, bright eyes, and that unmistakable spark of possibility. Children race ahead, fingers trailing along banisters and baseboards, already assigning beds and secret hideouts. Parents move more deliberately, pausing in doorways to imagine morning routines, dinner gatherings, and where the artwork will hang. Couples exchange looks that say “this could be ours,” practicing small decisions—“kitchen this way or that?”
Those moments are full of stories in miniature: a grandmother touching a windowsill and picturing afternoon quilts and tea; a young family mapping out a home office in a sunlit corner; roommates debating which bedroom gets the balcony. Even the smallest details take on meaning—the way light falls through a bay window, the creak of a stair that suddenly feels charming, the pantry that seems to promise Sunday baking.
Open houses are less about transactions and more about imagining futures. They reveal how homes are more than walls and floors: they are stages for birthdays, homework sessions, quiet mornings, and loud holiday dinners. Seeing people already living in a space—if only in their minds—reminds you why houses matter. The smiles, the quiet plans, the shared laughter: all of it is a testament to hope and the simple human desire to belong.
If in 2026 you are ready. lets connect
If in 2026 you’re ready to buy or sell, let’s connect. Here’s how we can start the conversation:
Tell me what you need
Buying: preferred locations, budget, must-haves, timeline.
Selling: property address, asking price range, current condition, timeline.
Choose the best contact method
Call or text: [818] 46646-31
Email: antonio.chavez@kw.com
Quick form: reply with “Contact” and your preferred method and availability.
Share key documents or info (if available)
Pre-approval letter (buyers)
Recent mortgage statement (sellers)
MLS link or listing details
Photos or a brief property summary
Schedule a first step
Buyer: virtual or in-person consultation and a list of suitable homes.
Seller: market analysis and suggested pricing/repair recommendations.
What to expect next
I’ll respond within 24 hours with a tailored plan, next steps, and suggested meeting times.
We’ll agree on clear timelines, communication preferences, and goals.
Ready when you are. Reply with “Ready to connect” and your preferred contact method or drop the details above to get started.
Subscribe to Our Newsletter for Essential Real Estate Updates
Stay informed with timely market insights, exclusive property alerts, and expert tips tailored to your home search. Subscribe to our newsletter and receive:
Instant listings that match your preferences
Market trends and neighborhood updates
Buying and selling guidance from trusted professionals
Alerts on price changes and new opportunities
Practical tips for financing, inspections, and moving
Sign up today to get the information that matters delivered straight to your inbox. Stay ahead in the market — let us help you find your ideal home.
A Common Objection I’m Hearing Lately… “I need to wait”
It’s an objection many real estate agents are hearing right now—and on the surface, it’s actually a logical way to think.
The real issue isn’t the question itself.
It’s where the information is coming from.
Most consumers today are being conditioned by national headlines, viral social media commentary, and broad market narratives that have little—or nothing—to do with what’s actually happening in their local market.
Real estate is hyper-local.
What you hear on the news doesn’t always reflect what’s happening on your street, in your neighborhood, or with homes like yours.
That’s why working with a local professional matters—someone who understands the data, the trends, and the real opportunities specific to your area, not just the national noise.
If you’re making decisions based on headlines alone, you may be missing what’s really happening right in front of you.
As of today Mortgage rates
Mortgage Rate Update — September 4, 2026
Mortgage rates remain elevated as we head into September. According to Freddie Mac’s latest weekly survey, the average 30-year fixed mortgage is 6.71%, up from 6.66% the previous week. The average 15-year fixed mortgage is 6.04%.
Daily market averages can be somewhat higher. Bankrate’s September 4 national average for a 30-year fixed purchase mortgage is about 6.83%, with an APR around 6.89%.
For buyers, the key is not to focus on one headline rate. Your actual mortgage rate will depend on factors such as credit score, down payment, loan type, points, and lender pricing.
For sellers, higher borrowing costs continue to make buyers very sensitive to the monthly payment, which makes realistic pricing and possible seller concessions increasingly important.
Bottom line: rates remain in the upper-6% range, so buyers should compare lenders carefully and sellers should understand how financing affects what buyers can comfortably afford.
📲 Let’s talk about how this market update affects your plans for 2026.
— Antonio Chavez
📞 818-466-4631
🌐 achavez65.kw.com

The possibilities to own your home are many when there is determination.
Set a clear goal. Decide the type of home, preferred neighborhoods, and timeline. Break the goal into steps: save for a down payment, improve or maintain credit, get pre-approved for a mortgage, and research local market trends.
Explore financing options. Conventional loans, FHA, VA, USDA, and local first-time buyer programs each have different requirements and benefits. Compare interest rates, down payment options, and closing costs. Consider assistance programs, grants, or employer-supported homebuying benefits that can reduce upfront costs.
Create a realistic budget. Account for mortgage payments, property taxes, insurance, maintenance, utilities, and potential homeowners association fees. Build an emergency fund for unexpected repairs or income interruptions.
Use personalized search tools and alerts. Set filters for price range, size, schools, commute time, and must-have features. Get notified when new listings match your criteria so you can act quickly in competitive markets.
Work with experts. A knowledgeable real estate agent can help identify suitable properties, negotiate offers, and navigate inspections and closing. A mortgage broker or lender can clarify loan options and pre-approval. An attorney or title company can ensure a clean transfer of ownership where required.
Be prepared to compromise. Prioritize your must-haves versus nice-to-haves. In some markets, flexibility on features or location can make homeownership feasible sooner.
Consider alternative paths. Rent-to-own agreements, co-buying with family or friends, buying a fixer-upper, or investing in manufactured housing are viable routes for some buyers. Each option carries different risks and responsibilities—evaluate them carefully.
Stay persistent and adaptable. Markets change, and setbacks can occur, but determination paired with planning, expert guidance, and timely action significantly increases your chances of owning a home. Contact us to get personalized alerts and expert support tailored to your goals.
The process to own your home can be a call away. lets connect.


Our Services
Explore the range of services with down payment resources
Down payment assistance can make homeownership attainable sooner. At Homes by Antonio, we connect buyers with services and resources designed to reduce upfront costs and simplify the path to closing. Below is an overview of common down payment assistance options and how we help you access them.
Grants and forgivable loans
What they are: Direct funds that do not need to be repaid (grants) or loans that are forgiven after meeting certain conditions or a period of occupancy.
Who they help: First-time buyers, low- to moderate-income households, and buyers in targeted neighborhoods.
How we help: We screen programs you may qualify for, prepare required documentation, and coordinate with program administrators to speed approval.
Deferred-payment and low-interest second mortgages
What they are: Second loans used for the down payment that may have reduced interest rates or delayed payment start dates.
Who they help: Buyers who need assistance with upfront costs but have enough income for future payments.
How we help: We compare lender offers, explain payment terms, and integrate these options with your primary mortgage strategy.
Employer-assisted housing programs
What they are: Employer-funded grants, loans, or matching contributions toward down payments as an employee benefit.
Who they help: Employees of participating companies.
How we help: We identify employer programs, advise on eligibility, and assist with applications and paperwork.
Government programs (federal, state, and local)
What they are: Programs administered through FHA, USDA, VA, and state or municipal housing finance agencies offering low down payment loans, grants, or tax incentives.
Who they help: Varies by program—veterans, rural buyers, low-income households, and first-time buyers commonly qualify.
How we help: We match eligible buyers to appropriate programs and ensure your mortgage officer is coordinated with program requirements.
Community Development Financial Institutions (CDFIs) and nonprofit lenders
What they are: Mission-driven lenders offering flexible underwriting, lower fees, and specialized down payment assistance.
Who they help: Borrowers underserved by traditional banks or with unique financial situations.
How we help: We maintain relationships with CDFIs and refer clients to lenders likely to offer favorable terms.
Matched savings and Individual Development Accounts (IDAs)
What they are: Programs that match a portion of your savings toward a home purchase over time.
Who they help: Buyers able to save but needing


Why consider downpayment assistance now
Personalized search: We match you with listings that meet program requirements and price limits.
Expert guidance: We help identify local assistance programs and coordinate with lenders and housing agencies.
Instant alerts: Be the first to know when homes that fit your budget and program criteria hit the market.
Start your year with a plan. Contact us to learn which downpayment assistance options you qualify for and take the first step toward homeownership.


At Homesbyantonio.com, we constantly refine our tools, knowledge, and approach to make your home search faster, smarter, and more enjoyable. From sharper property alerts to smarter filters and candid, helpful insights, we blend data-driven updates with a touch of personality to keep the process efficient and human.
What that means for you:
Faster, more relevant listings delivered instantly.
Better-tailored search results that learn from your preferences.
Clear, practical guidance from agents who stay current on market trends.
A friendly, straightforward voice that keeps things simple (and occasionally witty).
Always improving. Always on your side.
I am here for you